A guide to the calculators
If you are buying a house to rent out and keep, start with the single-family rental analyzer. It takes a price, a rent and the running costs and tells you what lands in your account each month, what the property yields before financing, and what your own cash earns. For a small apartment building the multi-family calculator does the same job with the operating lines a building accumulates, and if you plan to live in one unit and rent the others, the house hacking calculator compares your housing cost against simply renting — and shows what the property does once you move out. Letting it nightly instead is a different business with its own arithmetic, which is what the short-term rental calculator is for.
If the plan is to improve a property rather than just hold it, the BRRRR calculator follows the buy, rehab, rent and refinance sequence and reports how much of your capital comes back out. The fix and flip calculator is for selling at the end rather than refinancing, and the wholesale calculator works backwards from what an end buyer could pay to whether your assignment fee fits inside it.
If the question is how a deal gets paid for, the DSCR loan qualifier shows whether the rent clears a lender's minimum and the largest loan it supports. The loan comparison calculator prices competing quotes over the period you will actually hold the loan, which is usually shorter than the term. The seller financing calculator and the wrap and subject-to calculator cover deals where the seller carries the note or an existing low-rate loan stays in place. And if you are weighing buying at all against continuing to rent, the rent vs. buy calculator runs both paths forward and reports the year one overtakes the other.
Every calculator shows its full arithmetic and explains what the result means, including where the number flatters a deal and where it understates one. Unfamiliar terms are defined in the glossary.
Market spotlight
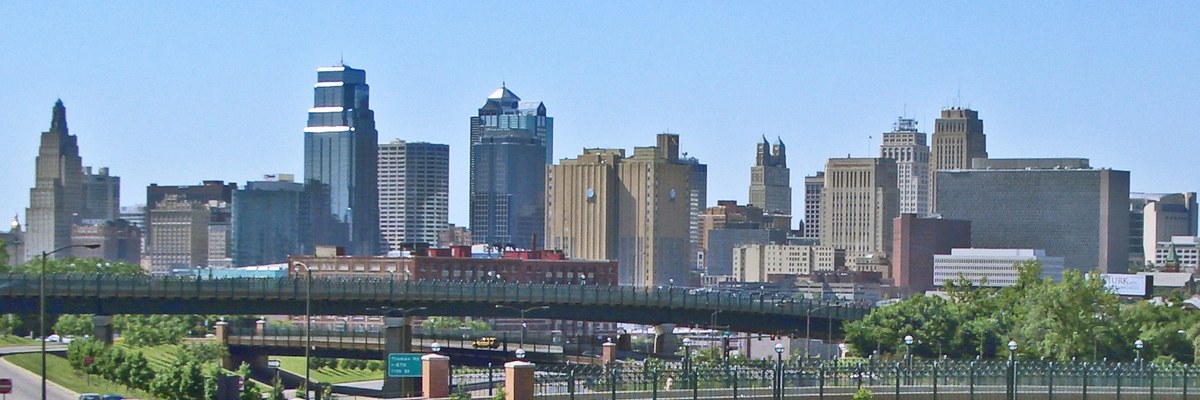
The largest market in this series, a 2.3x price spread between its submarkets, two states with different assessment systems, and one county the state has had to order corrected three times.
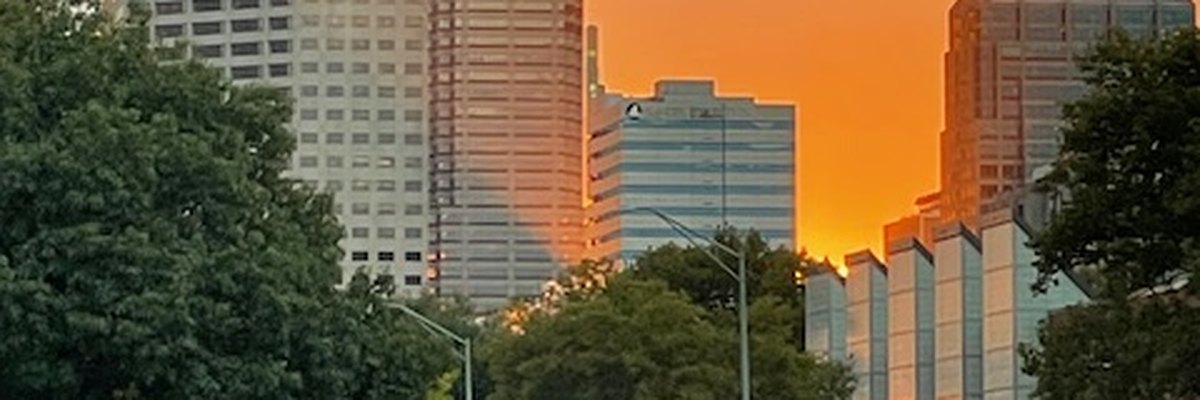
Strong rent against the purchase price, a rental market institutional buyers have been active in for years, and a property tax cap set at double the owner-occupant rate.
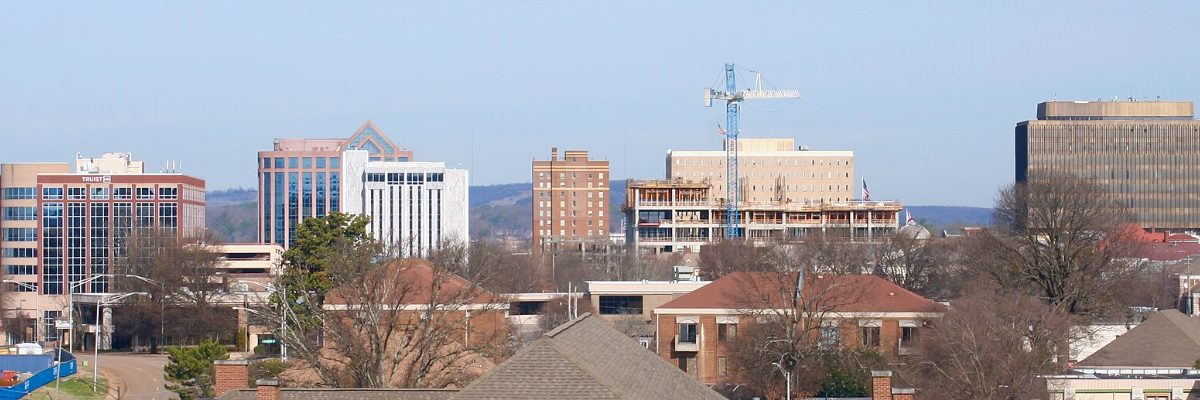
Population and job growth outpacing most of the Southeast, home prices finally cooling, and the defense-sector concentration risk worth modeling before you buy.
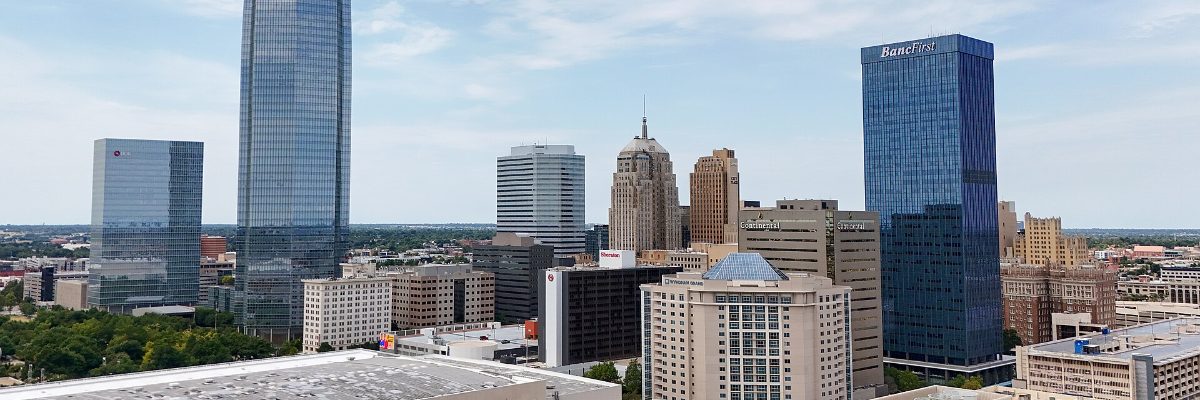
The rare market where population, jobs, rents and absorption all point the same way — and where the insurance line, not demand, decides the deal.
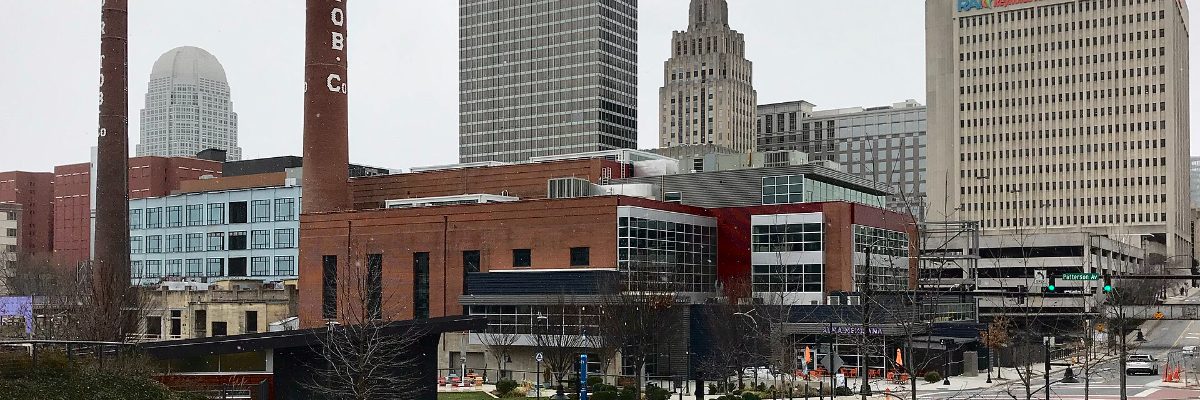
Two metros where the headline tax rate is genuinely the rate you pay — and one county where a 40% revaluation lands in the 2027 bill.
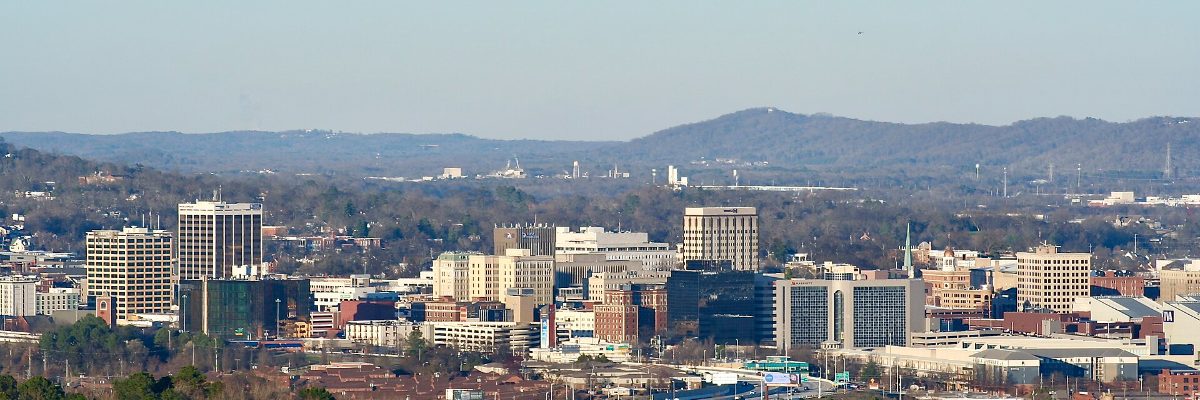
A genuinely diversified employment base, no owner-occupier tax penalty, and a two-unit threshold that raises your assessed base by 60%.
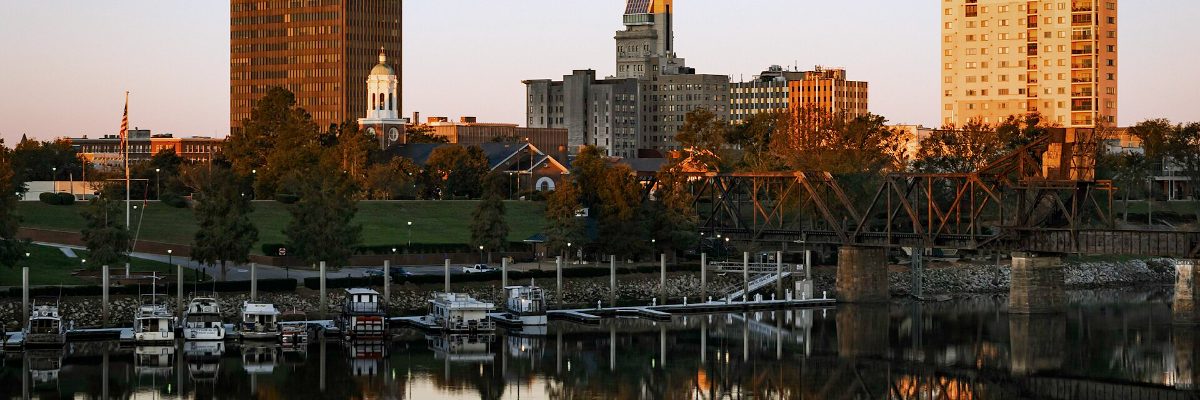
The cheapest entry in the series, a government-anchored job base that is currently shrinking, and a state line that changes the tax bill by half.
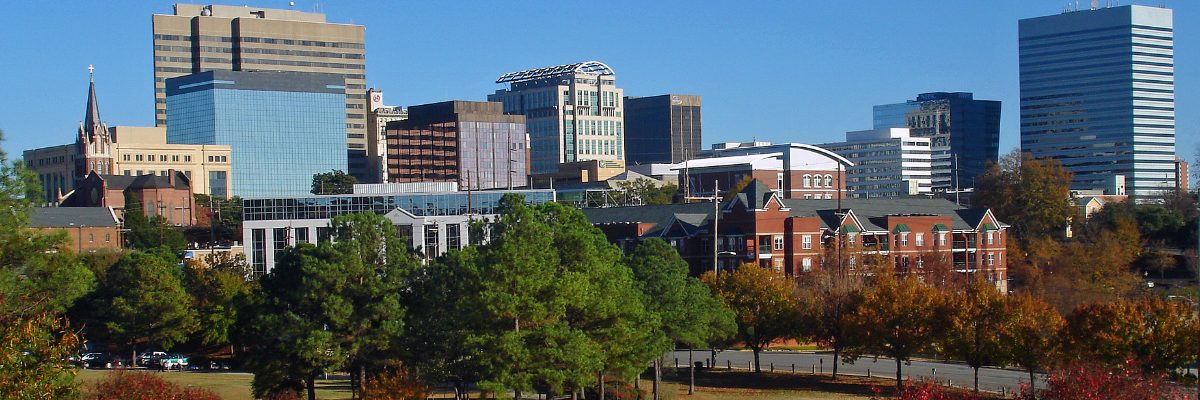
Strong in-migration, prices still well under the national median, and the property tax quirk every out-of-state investor needs to model before buying.
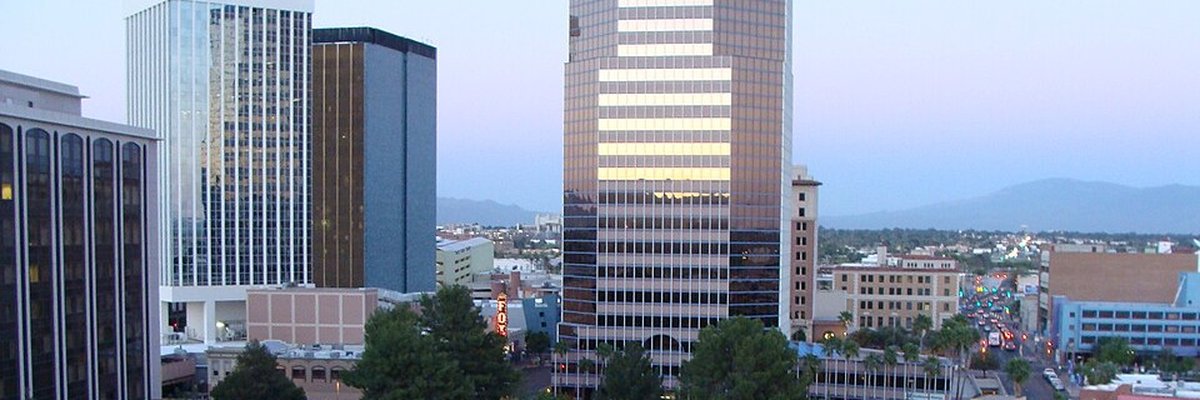
Strong rent against the price, a falling median sale price, and flat population and payrolls.
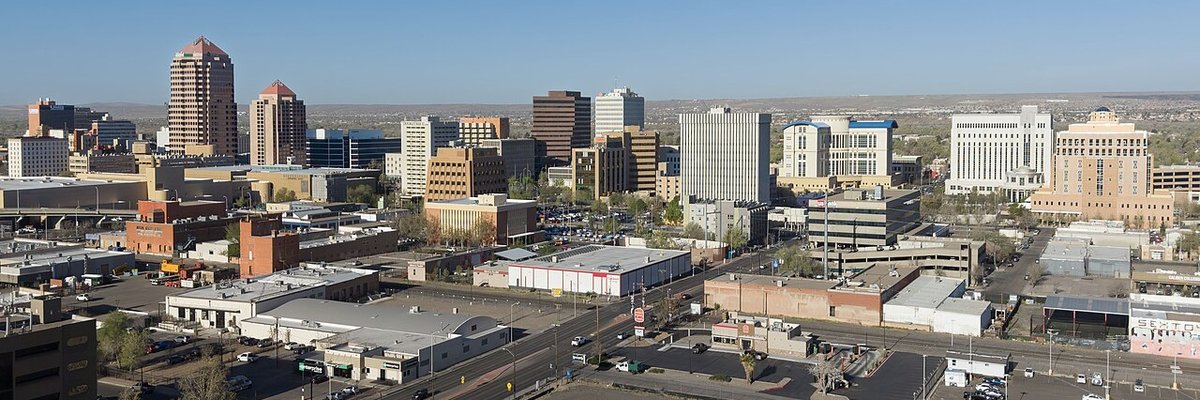
Strong rent against the price, shrinking payrolls, and sale prices that are not public record.
Market data
An interactive map of investor home-purchase share across 39 major U.S. metros, from Redfin's latest quarterly report.
From the ledger
The five inputs that make up a real rental underwriting, a worked example, and where a rushed one breaks.
What each metric actually measures, and why they can move in opposite directions on the same deal.
Setting realistic return targets by range, not by a single magic-number rule.
Why a 5% vacancy reserve is a long-run average, not what one real turnover actually costs.
Live in one unit, rent the others — the financing edge, and what happens after you move out.
The main ways to invest, side by side — what each asks of you and where the return comes from.
Higher revenue doesn't always mean higher cash flow once real STR expenses are included.
Buy, rehab, rent, refinance — where the cash actually comes from, and where deals go wrong.
What the 30% margin is actually covering, and where a flat rule breaks down.
Rate, appraisal, and lending-standard risk in the gap between purchase and refinance.
Same spread, two different mechanics — what changes in cost, privacy, and which contracts even allow it.
How lenders size a loan off the property's own rent, with no personal income required.
Why cash flow, cash-on-cash return, and cap rate don't all move together when you toggle financing.
Why "renting is throwing money away" misses what the down payment could have earned invested instead.
A calculator is only as good as its inputs — where rent, price, repair, rate, tax, and insurance numbers actually come from.
Plain-English definitions for every term used across the calculators — cap rate, DSCR, NOI, ARV, CapEx, and more.